Life insurance is often treated as something you buy once and keep indefinitely.
Your life does not work that way.
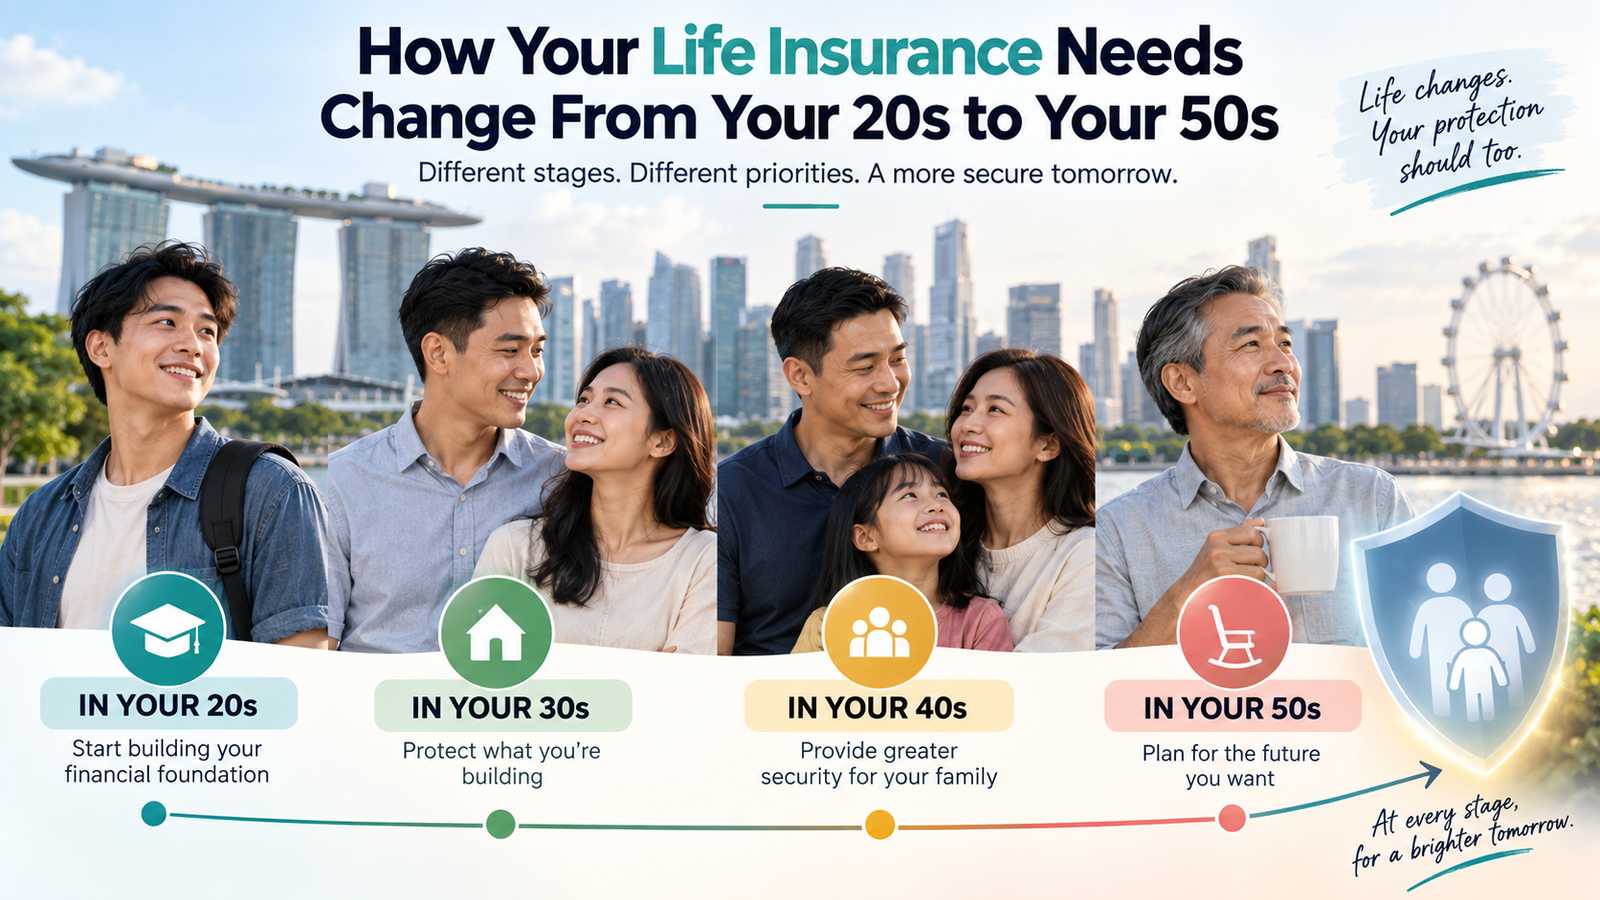
The financial responsibilities you have at 25 can look completely different at 35, 45 or 55.
You may get married, buy a home, have children, take on a larger mortgage or start supporting ageing parents. Later, those responsibilities may begin to reduce as your mortgage is repaid and your children become financially independent.
That means your life insurance needs should change too.
Rather than asking how much life insurance everyone should have, it is more useful to consider what you are protecting at each stage of life.
In your 20s: you may have fewer dependants
Someone in their 20s who is single, has no children and does not financially support anyone may have a relatively small need for death coverage.
If nobody relies on your income, there may be little income that needs replacing.
That does not mean insurance is irrelevant.
You may still want to consider areas such as health and critical illness protection, and some young adults already support their parents financially.
Your individual circumstances matter more than your age.
This is also a useful time to understand what insurance you already have rather than accumulating policies without a clear purpose.
Marriage: another person’s finances may become connected to yours
Marriage does not automatically mean you need a large life insurance policy.
But it is a good reason to review your protection.
Ask what would happen financially if either partner died.
Could the surviving spouse comfortably manage household expenses alone?
Are there joint debts?
Does one person earn significantly more than the other?
The more financially dependent each person is on the other’s income, the more important life insurance may become.
Couples should ideally discuss protection together rather than each person buying policies independently without looking at the household as a whole.
Buying a home: account for your mortgage
For many Singapore households, a home loan is one of their largest financial commitments.
When taking on a mortgage, think about what would happen to the loan if one income disappeared.
Some homeowners may have mortgage-related protection already. HDB owners using CPF for their housing loan, for example, may be covered under the applicable mortgage protection arrangements.
But you should still understand exactly what protection is in place and whether other household financial needs would remain.
Paying off a mortgage is only one part of supporting a family.
Having children: your protection needs may rise significantly
For many people, having children creates the biggest increase in their need for life insurance.
Young children may depend on their parents financially for another 15, 20 or even 25 years.
If a parent’s income disappears during that period, the surviving family may still need to pay for housing, food, childcare, school expenses and eventually higher education.
This is why parents often need substantially more life insurance than they did before having children.
The amount should not be chosen arbitrarily.
Estimate how much the family would need, how long they would need it and what other financial resources would be available.
Then subtract existing insurance and assets to work out the gap.
Your 30s and 40s may be the years of highest responsibility
This is often the stage when several financial commitments overlap.
You may have:
- Young children
- A substantial mortgage
- Ageing parents
- Household expenses
- Education goals
- Limited time to accumulate enough assets to replace your income
Someone in this position may need a relatively large amount of life insurance even if they already own several policies.
What matters is not the number of policies.
It is the total protection available compared with the family’s financial need.
This can also be a good stage to review whether the type of coverage you own still makes sense.
Some financial needs may only last for the next 20 or 30 years, while others may be lifelong.
Understanding that distinction can help when deciding between term insurance, whole life insurance or a combination of the two.
Your late 40s and 50s: some responsibilities may start to fall
Life insurance needs do not necessarily keep increasing as you get older.
Your mortgage balance may be much smaller.
Children may finish their studies and start working.
You may have accumulated CPF savings, investments and other assets.
As your financial position becomes stronger and fewer people depend on your income, the amount of life insurance needed for income replacement can fall.
This does not mean everyone should cancel their policies at 50.
Some people may still be supporting children or parents. Others may want permanent life insurance for estate planning or to provide for a dependant with long-term needs.
The point is that the calculation should be revisited.
The amount that was appropriate when you were 35 may no longer be the right amount at 55.
Retirement changes the calculation again
As you approach retirement, your financial life gradually shifts from earning and accumulating assets towards using the assets you have built.
If you no longer rely heavily on employment income and your dependants are financially independent, replacing your income after death may become less important.
Your assets may also be sufficient to support your spouse or family.
At this stage, some people still choose to maintain life insurance for different reasons, while others may find their protection need has reduced considerably.
Again, there is no universal number.
Review after major life events, not only at a certain age
Age is a convenient way to illustrate how life insurance needs change, but life events are actually the more important trigger.
Review your coverage when you:
- Get married
- Have a child
- Buy a home
- Take on a major loan
- Change jobs
- Start supporting parents
- Experience a substantial change in income
- Pay off your mortgage
- Have children become financially independent
These changes can materially affect how much protection your household needs.
How do you know how much life insurance you need?
Start with the financial consequences if you were no longer around.
Estimate your family’s living expenses, outstanding debts, children’s needs and any other people you support.
Then consider how many years those obligations will continue.
Next, subtract resources that are already available, including existing life insurance and assets that could reasonably be used to support your family.
The remaining amount gives you a better idea of your protection gap.
For consumers who want to work through the calculation and understand the available options, Planner Bee’s life insurance guide explains life insurance in Singapore, including how to estimate coverage and how term and whole life insurance differ.
Life insurance should move with your life
There is no single amount of life insurance that is correct from your first job until retirement.
Your protection needs are highest when the financial consequences of losing your income are highest.
As your family, debts, assets and responsibilities change, your insurance should be reviewed along with them.
The aim is not to continually buy more insurance.
It is to have enough protection for the responsibilities you actually have today, and to adjust it as those responsibilities change.